The Rule That Protected You Just Got Erased. Here's What That Means.
A federal judge quietly eliminated the standard that required retirement advisors to act in your best interest. Most people missed it. You shouldn't.
On March 12, a federal judge in Texas signed a one-page order that most of the financial media ignored. The Department of Labor didn't fight it. There were no press conferences. It didn't trend on social media.
But if you're within ten years of retirement, it may be one of the most consequential financial developments of 2026 for your household.
The judge vacated the Retirement Security Rule — the Department of Labor regulation that required advisors who recommend retirement account investments to act as fiduciaries. In plain English: the legal standard that said your retirement advisor must put your interests ahead of their own commissions just got erased.
What Happened
To understand why this matters, you need to understand a word that the financial industry has worked very hard to keep confusing: fiduciary.
A fiduciary is someone who is legally required to act in your best interest. Full stop. Not "suitable" for you. Not "not inappropriate" for your situation. Actually, demonstrably in your best interest.
Sounds like the obvious minimum standard for someone managing your retirement savings, right?
It isn't. And it never has been — at least not universally.
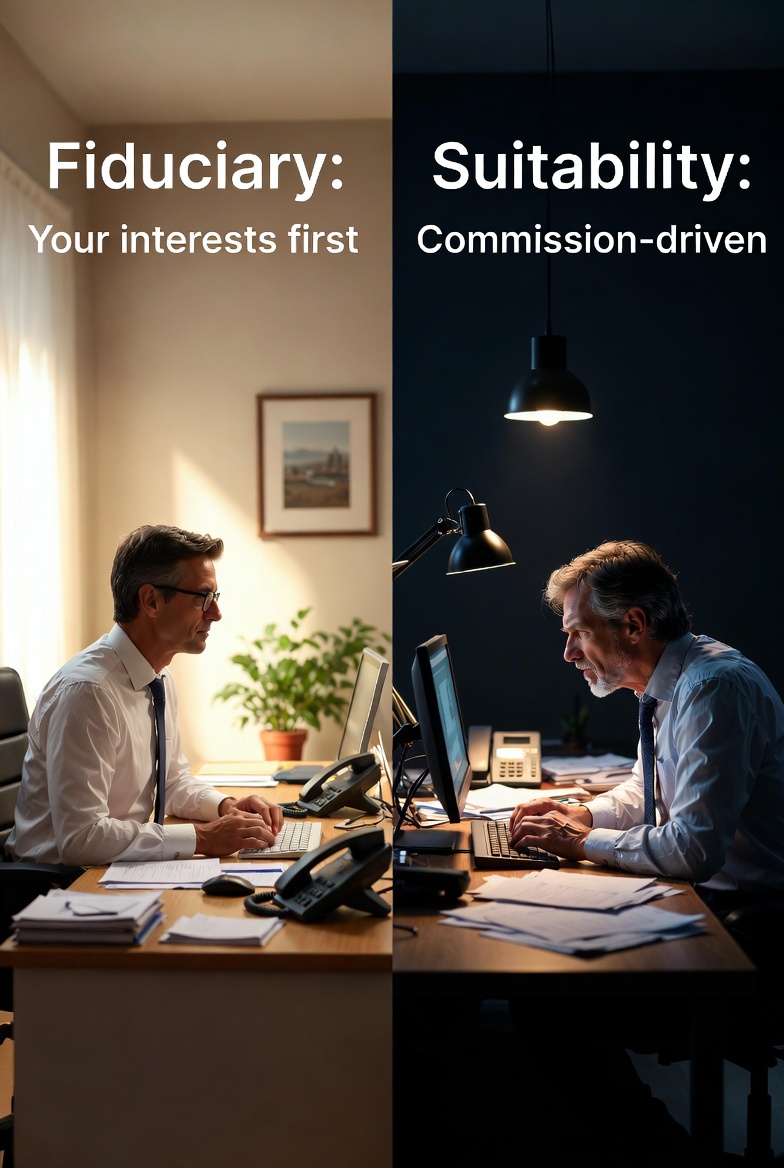
For decades, most brokers and insurance agents who sell retirement products have operated under a much looser standard called suitability. Under suitability, a recommendation is acceptable if it's not wrong for you — even if it happens to generate a much higher commission for the advisor than a cheaper alternative that would have served you better. You'd never know the difference.
The Retirement Security Rule, finalized in 2024, was designed to close that gap. It required anyone giving retirement investment advice — brokers, insurance agents, financial planners — to meet the fiduciary standard when working with retirement accounts. For a brief moment, the playing field was leveled.
That moment is now over.
What It Means for Me
Here's the direct consequence: the person selling you an annuity, a variable life insurance product, or a high-fee mutual fund for your IRA is no longer legally required to recommend the best option for you.
They can recommend something that earns them a higher commission — as long as it's not outright wrong for your situation. And they don't have to tell you that a lower-cost option exists.
This matters most to people in exactly your demographic. Pre-retirees are the most heavily marketed-to segment in financial services. You have accumulated real money. You are thinking about retirement income. You are often anxious about making the right choices. That combination makes you a target for products that are profitable for the seller — annuities with high surrender charges, variable products with layered fees, actively managed funds with expense ratios that quietly eat your returns.
None of those products are automatically bad. Some of them make sense for some people. But the difference between a fiduciary recommending one versus a suitability-standard advisor recommending one is enormous. A fiduciary has to justify why that product is best for you. A suitability-standard advisor just has to show it isn't harmful.
That distinction is now legally optional again.
There's a second-order consequence worth naming. You've probably seen the phrase "fee-only" or "fee-based" advisor in financial media, often used interchangeably. They're not the same. Fee-only advisors are compensated only by their clients — no commissions, no product revenue, no kickbacks. Fee-based advisors can still receive commissions on products they sell, even while charging you a management fee. This rule would have helped standardize the obligation on both types. Without it, the burden falls entirely on you to ask the right questions.
What We're Doing About It
Asset Guidance Group is a registered investment advisor. That registration carries a fiduciary obligation that doesn't depend on what rules the Department of Labor enforces or vacates. It's baked into our legal structure.
We don’t earn commissions on the products we recommend unless we find a situation specifically requiring an insurance product AND that product is in the client’s best interests AND the client wants that product. That’s a small percentage of cases. We are overwhelmingly compensated by our clients— not by fund companies, insurance carriers, or anyone else with an interest in what we put in your portfolio. That alignment is not a marketing line. It's the foundation of how we work.
I spent years as a litigator before I was a financial advisor. I have seen what happens when advisors are paid to sell products rather than solve problems. I built this firm specifically to be on the other side of that equation.
Here's what I'd suggest you do in the next two weeks. Look at whoever is currently giving you retirement investment advice. Ask them directly: "Are you a registered investment advisor with a fiduciary obligation to me? Are you compensated only by me, or do you receive commissions or revenue from any products you recommend?"
If the answer is unclear, or if they pivot to suitability language, that tells you something important. You deserve to know whose interests your advisor is serving.
The rule that was supposed to guarantee that answer just got erased. The question still needs an answer.
Before You Go
If this raised questions about your own advisor relationship — or if you want to understand exactly what fiduciary obligation means in practical terms for your retirement — I'm happy to have that conversation.
assetguidancegroup.com/ats-mgmt-landing-page-347034
[email protected] | assetguidancegroup.com/calendar
───This post originally appeared on The Lighthouse on Substack — weekly financial analysis written specifically for people within ten years of retirement. Subscribe free at [The Lighthouse on Substack] or upgrade for weekly Trades of the Week picks.───
Investing involves risk, including the possible loss of principal. This article is for informational purposes only and does not constitute personalized investment advice. Past performance is not indicative of future results.
Wallace R Nichols, MBA, JD, CFP Chief Investment Officer Asset Guidance Group, LLC, a registered investment advisor



