Take Control of Your Retirement Security-- Don't Leave Your 401(k) Behind!*
How prepared do you feel for retirement?
Savings are falling short while inflation, healthcare, and other costs increase. On average, Americans believe theywill need $1.46 million to retire comfortably. But the average US adult has $88,400 saved for retirement--a $1.37 million gap!**
**Northwestern Mutual, Planning and Progress Study 2024
*This page applies equally to other types of employer-sponsored retirement plans, e.g., 403(b), 457(b), 457(f).
Your retirement plan is an essential asset. DON'T LET IT GO UNMANAGED!
Mitigate risks and optimize opportunity
Benefit from proactive review and rebalancing that’s responsive to market conditions and informed by financial analysis –just like your other assets.
Maximize savings with tax-aware retirement investment strategies embedded into your holistic financial strategy.
Take better control of your retirement security
Reduce Costs and increase your options
Don't default to a target-date fund (TDF) without checking whether its costs and investment mix fit your situation.
Do Less, Achieve More
And that's where Asset Guidance Group comes in!

Save time on self-directed research and leverage the expertise of your trusted advisor.
Potential to add 3% more value annually, net of fees, with professional management.
Vanguard, Putting a value on your value: Quantifying Vanguard Advisor's Alpha, 2022.


Achieve your retirement goals
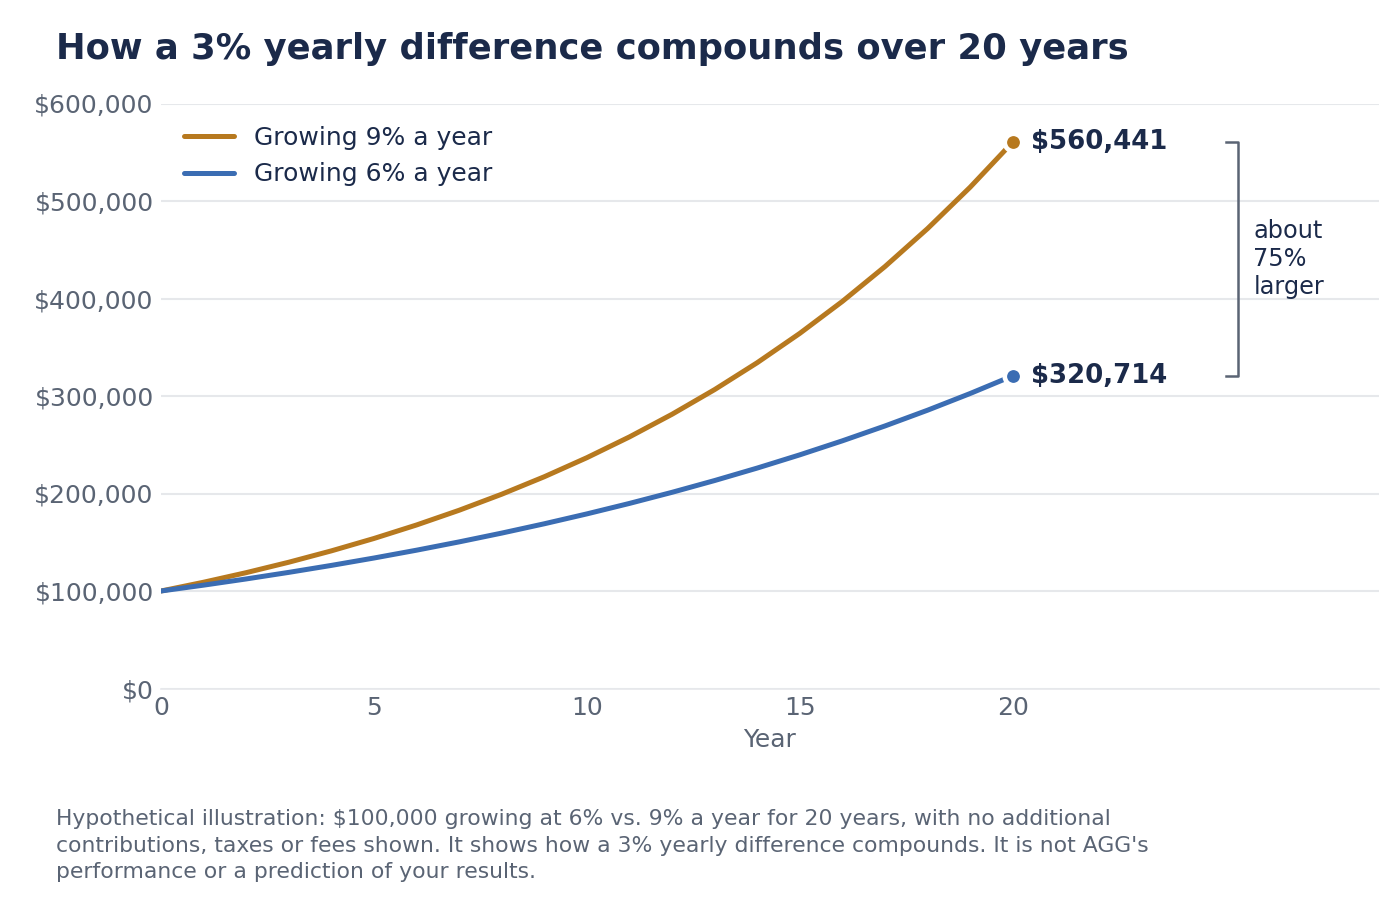
You’ve worked hard to build up your savings. Make your savings work for you— research estimates that professional advice can add up to about 3% a year in net returns, and sometimes more, compared with managing on your own. Results vary and are not guaranteed.3 When you enable your advisor to provide tailored financial guidance, consider this: a 3% yearly difference, over 20 years, adds up to a balance about 75% larger. Putting a value on your value: Quantifying Vanguard Advisor's Alpha, Vanguard, 2022.
READY TO GIVE US A TRY?
Discover the Benefits of Professional Plan Management

Conquer information overload
Effectively managing your investments and making informed financial decisions takes time, skill, and effort. You’ve hired your financial advisor to provide professional guidance, but there has been an important piece missing– the ability for your advisor to oversee your 401(k). With the new software we use, as your trusted wealth advisor, we gain the ability to proactively manage your 401(k) as part of your entire portfolio, so you can skip deciphering lengthy plan information and fund options on your own.
Unlock your saving potential
Managing your 401(k) accounts separately from the rest of your assets can create a siloed view that prevents you from taking full advantage of asset allocation and tax strategies. Pontera enables your advisor to holistically manage all of your financial accounts according to your personalized financial plan.
READY TO GIVE US A TRY?
Discover how our tailored strategies can enhance your plan's performance.
Click the Book a Meeting Now!
What if you're currently in a Target Date Fund?
If you have a 401(k), 403(b), or 457 plan, you may have used a target-date fund ("TDF"). When you open your 401(k), you may select a "target date" year of retirement, pick a TDF, and then the TDF automatically selects investments for you. Most 401(k) plans offer TDFs.* But is a TDF right for you?
TDFs can work for you when:
You don't have outside investments
The majority of your household assets are in a 401(k)
Your finances are simple (not yet working with an advisor).
A Federal Reserve survey found that nearly 6 in 10 non-retirees with self-directed retirement savings had low comfort making investment decisions with those accounts. So TDFs can be an easy way out of making the decision about how to invest an employer-sponsored account such as a 401(k). But while TDFs are easy to use for new investors, TDFs get more conservative as you near retirement. Worse, TDFs, by definition, are not integrated into, and are not customized to, your unique financial needs and to the financial plan that you need built for you and your family.
*Federal Reserve Board, Economic Well-Being of U.S. Households in 2021 (2022).
Why Target Date Funds are probably letting you down
Target Date Funds (TDFs) have been widely adopted as a convenient investment vehicle, particularly in retirement plans like 401(k)s. However, these funds have recently come under significant scrutiny from both industry experts and regulatory bodies for several key issues:
1. Unsuitable Allocations
Despite their widespread use, not all TDFs are created equal, and their asset allocations can vary significantly even among funds targeting the same retirement year. This lack of standardization can lead to unsuitable allocations for investors, especially those who may not have the expertise to evaluate these differences. For example, some funds may maintain a high equity exposure close to retirement, increasing risk at a time when stability is more critical.8, 9
2. Hidden Fees
One of the most troubling aspects of TDFs is the layered fee structure. Many TDFs invest in other funds within the same fund family, which often leads to double-dipping on fees. Investors might not only pay for the management of the TDF itself but also incur fees from the underlying funds. These hidden costs can significantly erode returns over time, resulting in a substantial reduction in retirement savings. Research has shown that these fees can contribute to a cumulative return loss of up to 21% over a typical investment horizon.10, 11
3. Conflicts of Interest
TDFs are often marketed as a "set it and forget it" solution, appealing to less sophisticated investors who prefer not to actively manage their portfolios. However, this simplicity can mask conflicts of interest. Fund managers may prioritize their financial institution's products within the TDF, even when better-performing or lower-cost options are available elsewhere. This lack of accountability can lead to underperformance and ultimately undermines the investor’s long-term financial goals.12
Given these concerns, it's crucial for investors to perform due diligence when selecting a Target Date Fund. Understanding the specific allocations, being aware of potential hidden fees, and recognizing the inherent conflicts of interest are essential steps to ensure that your retirement savings are optimized for your future.
___________
Sources:
What Happens to Your Target Date Fund When You Hit Retirement Age, Kiplinger: Why Target Date Funds Miss the Mark
Kiplinger: The Disturbing Conflicts of Interests About Target Date Funds
Kiplinger: Three Reasons Why Target Date Funds are Not Right for Anyone
Kiplinger: The Disturbing Conflicts of Interests About Target Date Funds
When professional management may be best
As we've mentioned, TDFs are not customized to your unique financial needs and to the financial plan you need built for you and your family. As your advisor knows your goals for finances and for life, you need to make sure these accounts are set to achieve them. Aside from allowing your advisor to better customize your asset allocation to your financial goals, the advisor will be able to optimize your portfolio for taxes through asset allocation strategies. This is not possible if your 401(k) is invested in a target date fund that is not coordinated with the rest of your investment accounts.
So, if you're working with a financial advisor, it's time to consider your 401(k) as part of your full financial life for comprehensive management. You advisor can make sure your investments:
are diversified to lower risk and increase opportunities for higher returns
work in harmony with your personal risk tolerance, with your goals at the forefront:
personalized planning, not one-size-fits--all
balance with all of your assets
professional review of performance & fees
comprehensive retirement income planning
cohesive financial strategy pre-and post-retirement
minimized taxes with asset allocation
The difference professional management can make
We've shown you on this page that research estimates professional advice can add up to about 3% a year in net returns, and sometimes more. Over 20 years, a 3% yearly difference adds up to a balance about 75% larger. Results vary and are not guaranteed.
As you near retirement, you need a more tailored plan, and your financial advisor can help you reach your goals.
That being said, we'd like to apply for the job of being your manager! If you'd like to speak with us about this, click the button below.
____________
Sources:
Putting a value on your value: Quantifying Vanguard Advisor's Alpha, Vanguard 2022
Ready to bring your 401(k) into your full plan?
Book a free consultation to see how we'd manage it alongside the rest of your money.
Life is full of unexpected changes, both at the personal and global level. Whether celebrating a major milestone or navigating a volatile market, retirement savers tend to make better decisions in the face of uncertainty when working with us as your financial advisor. Signing up with Asset Guidance Group as your financial advisor allows us to proactively rebalance your accounts during market volatility, and that service alone can spell the difference between meeting your retirement goals or ultimately falling short.
Contact us now to discuss your retirement goals and explore customized plan options tailored to your needs. Don’t miss out on the opportunity to benefit from expert guidance and innovative retirement solutions.
Get Peace of Mind
Our interface with you 401(k) plan custodian is bank-level secured
Protecting your financial wellbeing is our top priority and that of our third-party vendor technology provider, Pontera. Our goal is to ensure that retirement savers are able to receive the advice and support they need while their account remains secure. Pontera enables us to manage retirement accounts without direct account access, shared credentials, nor the ability to withdraw funds. In addition, Pontera is a SOC 2 certified business that uses the latest cybersecurity and data protection technologies to safeguard your financial account information. Pontera's robust cybersecurity and data privacy strategies are underpinned by Zero Trust Architecture and compliant with globally-recognized standards including SOC 2 Type II Certification by Ernst & Young and ISO/IEC 27001 compliance as certified by an accredited ISO body. For a comprehensive discussion of cybersecurity measures in place, visit Pontera's disclosure on client-protection page by clicking this link.
Explore Your Personalized Retirement Options—See More Now!
Book now and let's learn about you and your goals. You are losing money every day until you take action now!
By clicking the button below, you can schedule a Zoom meeting. This will allow you to select a convenient time to discuss your personal situation with us. Our bot will send you a notice you can put on your calendar so you won't miss it. Better yet: neither of us have to deal with traffic!
Get In Touch